
Category: Dow Jones

20 Mar 2026

AG MARKET UPDATE: MARCH 3 – 20

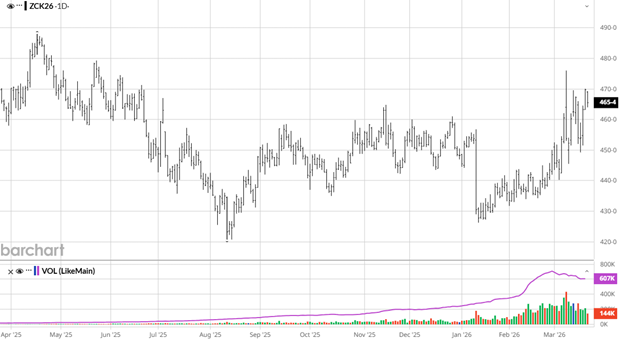
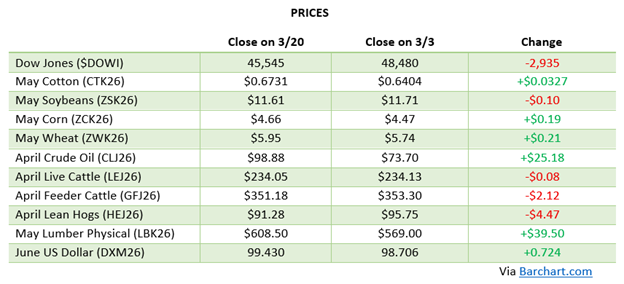
Corn has transitioned from early-week weakness into a volatile but constructive rally, driven far more by macro forces than traditional supply-and-demand fundamentals. Since the start of the Iran conflict, rising crude oil and diesel prices have injected inflation-driven buying into the grain complex, helping corn recover from Monday’s sharp losses and push higher into the end of the week. At the same time, the market is actively weighing the real impact of elevated input costs, particularly nitrogen, which could pull U.S. planted acreage below key thresholds near 94 million acres and provide longer-term support. However, that bullish narrative is being offset by softer export demand, limited Chinese participation, and concerns that high freight costs could further hinder competitiveness. With speculative funds now holding a large and increasingly crowded long position, corn remains technically supported but vulnerable to sharp corrections, especially if energy markets stabilize or geopolitical tensions ease.

Via Barchart

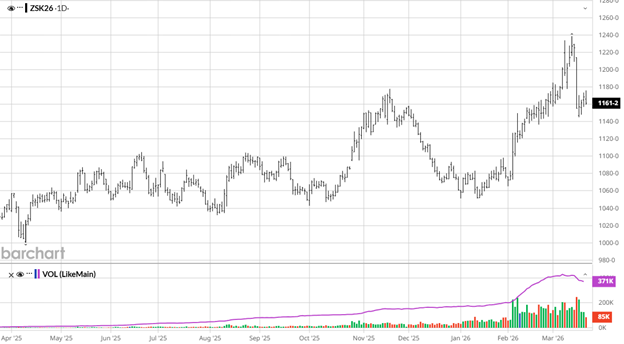
Soybeans have been the most volatile market of the complex, starting with a dramatic limit-down selloff early in the week tied to delayed U.S.-China trade talks and fading optimism around biofuel policy, before rebounding alongside strength in crude oil and the broader commodity space. Despite the recovery, the underlying fundamentals remain more bearish relative to corn, with record South American production, ongoing harvest pressure, and expectations for increased U.S. soybean acreage (potentially 85–86+ million acres) all weighing on the outlook. The earlier optimism around Chinese demand has cooled significantly, and with funds still holding a sizable position even after liquidation, rallies may continue to be sold. While inflation-driven money flow has provided temporary support, soybeans appear to be on more fragile footing, particularly if energy markets lose momentum or if acreage shifts materialize as expected this spring.

Via Barchart

Equity Markets

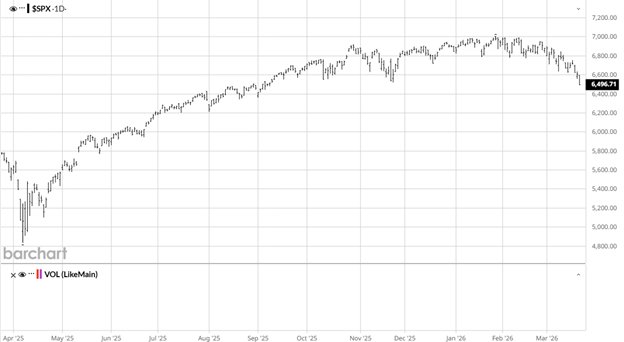
Over the past two weeks, equity markets have come under increasing pressure as investors grapple with the inflationary shock driven by surging energy prices and escalating geopolitical tensions surrounding Iran and the Strait of Hormuz. Early in the period, equities found brief support from a pullback in crude oil and optimism around global trade discussions, but that strength quickly faded as oil resumed its rally and inflation data came in hotter than expected. The Dow Jones Industrial Average has fallen sharply, shedding roughly 1,200+ points from recent highs and pushing to multi-month lows, as fears of a prolonged period of elevated fuel costs raise the risk of a global economic slowdown or recession.
Via Barchart

Other News

  • Energy markets had been volatile as the Straight of Hormuz remains closed with the war in Iran continuing.
  • Inflation is heating up a little but as energy prices surge, it causes ripples across the entire supply chain.


Drought Monitor

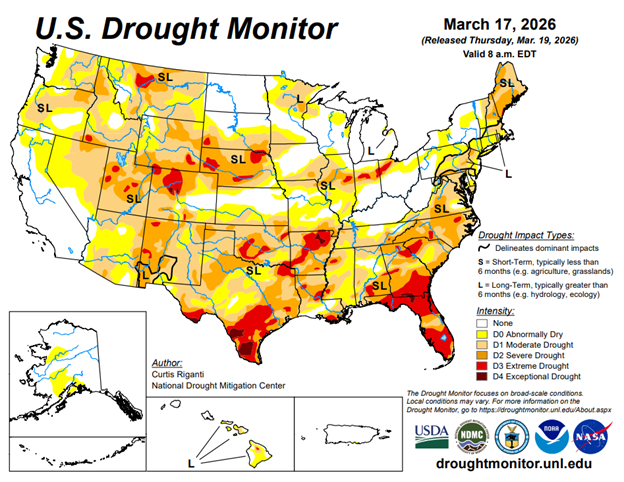
Here is the most recent drought monitor. With planting starting later this spring, we need rain in a lot of places in March.
Contact an Ag Specialist Today

Whether you’re a producer, end-user, commercial operator, RCM AG Services helps protect revenues and control costs through its suite of hedging tools and network of buyers/sellers — Contact Ag Specialist Brady Lawrence today at 312-858-4049 or blawrence@rcmam.com.


03 Mar 2026

AG MARKET UPDATE: JANUARY 12 – MARCH 3

Corn fundamentals remain quietly supportive. Domestic demand continues to provide a steady floor, with ethanol grind holding firm amid workable processing margins. Feed demand has also remained intact, supported by stable livestock numbers. Export business has been competitive but not aggressive, as global buyers weigh U.S. offers against South American supply. Overall, stocks are comfortable but not burdensome, keeping the downside limited while failing to create urgency on the upside. From a technical perspective, corn futures have respected both support and resistance levels throughout the month. The market continues to trade sideways, with carry in the futures structure signaling that end users are not pressed for immediate coverage. Until a weather premium develops or export demand accelerates meaningfully, rallies have tended to stall near the upper end of the range.

Via Barchart

Soybeans continue to be shaped by global supply clarity. South American production is largely known, which has limited the market’s ability to price in uncertainty. Domestic crush demand remains a supportive feature, particularly as renewable fuel feedstock demand underpins usage. However, export competition has kept shipments steady rather than explosive. The soybean market has struggled to sustain rallies, repeatedly testing higher levels before fading. Technically, the contract structure suggests hesitation from speculative buyers, with range-bound behavior dominating trade. Without a clear acreage shift or early-season weather concern, soybeans appear anchored between steady demand and comfortable global supply.

Via Barchart

Equity Markets

Equity markets traded with higher volatility over the past month as investors weighed solid economic data against persistent inflation concerns and firm energy prices. Major indexes moved within broad ranges rather than establishing sustained trends, with noticeable sector rotation throughout the month. Energy and defensive sectors generally outperformed, while rate-sensitive growth stocks faced intermittent pressure. Overall, the tone shifted toward cautious positioning, with investors quicker to trim risk on rallies while still supporting markets on pullbacks.

Via Barchart

Other News

  • Energy markets had been steadily moving higher heading into the weekend before the US bombed Iran which led to gains to start the week. How long the conflict lasts will be important to the global supply chain of oil.
  • Wheat is off recent lows but sold off from Monday’s high, the recent gains were needed but will need a little more help to get and stay above $6.

Drought Monitor

Here is the most recent drought monitor. With planting starting later this spring we need rain in a lot of places in March.

Contact an Ag Specialist Today

Whether you’re a producer, end-user, commercial operator, RCM AG Services helps protect revenues and control costs through its suite of hedging tools and network of buyers/sellers — Contact Ag Specialist Brady Lawrence today at 312-858-4049 or blawrence@rcmam.com.


14 Nov 2025

AG MARKET UPDATE: OCTOBER 27 – NOVEMBER 14

Corn’s Thursday rally was met with a post report Friday dip and gave up 10 cents back to $4.30. Despite the late season crop problems of drought and rust, the USDA did not find the corn yield loss that was expected and came in with a 186 bu/ac estimate, higher than the trade estimate. With higher production came higher US ending stocks, but those were not raised as much as yield as corn exports and domestic industrial demand has been exceptional this fall. The chart still looks constructive, but after a 30-cent rally in one month, the market will look to take a breather, especially after today’s report.

Via Barchart

Beans have been on a great run higher, albeit with some volatility, until Friday’s USDA report. Coming in that hot to a report can lead to a let down which we saw to some extent. The bean yield numbers were not as surprising as corn, coming in close to estimates, but the market still took a hit. The number to look at was the US held bean imports to China unchanged at 112 MMT for the 25/26 marketing year. A flash sale report did show sales of 1.1 mbu to China around the time the trade deal was in the works. The delayed data is hard to fit with all the other news out there but China buying anything is a good sign.

Via Barchart

Equity Markets

Equity markets have been volatile the last few weeks as worries of an AI bubble continue and several large companies such as Palantir, Meta and Oracle are well off their 52 week highs. Volatility will likely remain in the market for a bit as we will get caught up on economic data that was missing during the government shutdown.

Via Barchart

Other News

  • The wheat numbers were bearish as domestic and world stocks continue to climb on record world yields in all producing countries and exporters finding exports difficult to come by even at rock bottom prices. Wheat will remain an anchor on corn rallies.
  • Cotton adjustments show 900K more bales of US production, 200k more bales of US exports, and 700K more bales of US ending stocks compared to September.

Drought Monitor

Here is the most recent drought monitor as harvest rolls on.

Contact an Ag Specialist Today

Whether you’re a producer, end-user, commercial operator, RCM AG Services helps protect revenues and control costs through its suite of hedging tools and network of buyers/sellers — Contact Ag Specialist Brady Lawrence today at 312-858-4049 or blawrence@rcmam.com.


15 Sep 2025

AG MARKET UPDATE: AUGUST 29 – SEPTEMBER 12

Corn continued to move higher off last month’s lows following the September USDA Report. Most of the numbers came in along estimates but they increased planted acreage 1.4 million acres. This brings the US corn crop to 98.7 million acres, a new record. With about 90 million acres expected to be harvested, we will harvest 7 million more acres this year than in 2024, which equates to about 2 billion bushels larger crop than last year. Despite the added acreage corn bounced post report as weather issues, a dry finish, and disease pressure have caused speculation on the real size of this crop. As harvest gets rolling we will learn more about this crop.

Via Barchart

The USDA Report did not have any surprises for beans as most numbers were close to estimates, but the report could be viewed as slightly bearish. To get beans moving higher, China needs to show up as a buyer and trade talks with China need to make progress. China and the US are reportedly close to a deal over Tik Tok which can hopefully build some momentum for progress between the two countries. The size of the soybean crop, like corn, has been hurt by lack of rains down the home stretch but with the solid start the end result is still in question as harvest rolls.

Via Barchart

Equity Markets

Equity markets continue to make new highs with the Federal Reserve expected to start cuts this month. With the downward revision of 911,000 jobs from March ‘24 to March ’25 the labor market weakness gives the Fed some ammunition to lower rates with unemployment being one of their mandates.

Via Barchart

Other News

  • Secretary Rollins is in the process of looking into payments to farmers for this year with the low prices.
  • The wheat numbers were actually a bit supportive but lower world cash prices (Black Sea mainly) continue to plague prices. Wheat will remain an anchor for any potential corn rally as more wheat will be swapped in for corn in feed. Prices are back testing the 5 ½ year Covid lows.

Drought Monitor

Here is the most recent drought monitor as harvest begins.

Contact an Ag Specialist Today

Whether you’re a producer, end-user, commercial operator, RCM AG Services helps protect revenues and control costs through its suite of hedging tools and network of buyers/sellers — Contact Ag Specialist Brady Lawrence today at 312-858-4049 or blawrence@rcmam.com.

Check it Out:

Bulls, Bears, and Beef: Risk Management When Prices Run Hot

12 Aug 2025

AG MARKET UPDATE: AUG 4 – AUG 12 USDA REPORT

188.8 bu/acre… Hard to find a silver lining in the report for corn as the USDA ripped the band-aid off from the start instead of slow playing it. The average trade guess was 184-185 bu/ac which led to a big selloff seeing new contract lows. On top of the big yield number the USDA took the FSA planted acreage data and added 3 million acres in planted corn. The extra yield and acres could add nearly an extra 1 billion bushels of corn to the US and world ending stocks. The report did nothing to help the direction corn has been trading.

Via Barchart

The bean yield was also above pre-report estimates, coming in at 53.6 bu/acre. Prices were higher though following the 3 million acre planted acreage cut and total production cut by 90 million bushels. The market was caught off guard by the 3 million acre shift as evidenced in the opposite price reaction to the report numbers. The bean rally will give farmers a chance to catch up on sales but it will also motivate more acres to be planted in South America on stronger prices.

Via Barchart

Equity Markets

Equity markets continued to perform well as AI and tech companies are still the major movers. Nvidia and Microsoft are now a combined 15+% of the S&P 500 index, causing some to worry about concentration, but luckily they are performing well so right now a rising tide raises all boats (money in S&P ETFs).

Via Barchart

Other News

  • Wheat was in line with re-report estimates and had no major surprises. The weakness in corn will continue to weigh on wheat however.
  • Cotton saw a boost post report after the USDA lowered planted and harvested acres. Production was trimmed by 1.39 million bales to 13.21 million bales.

Drought Monitor

Here is the most recent drought monitor.

Contact an Ag Specialist Today

Whether you’re a producer, end-user, commercial operator, RCM AG Services helps protect revenues and control costs through its suite of hedging tools and network of buyers/sellers — Contact Ag Specialist Brady Lawrence today at 312-858-4049 or blawrence@rcmam.com.
 

13 Jun 2025

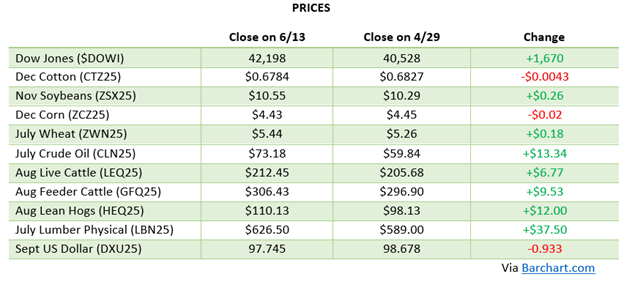
AG MARKET UPDATE: APRIL 29 – JUNE 13

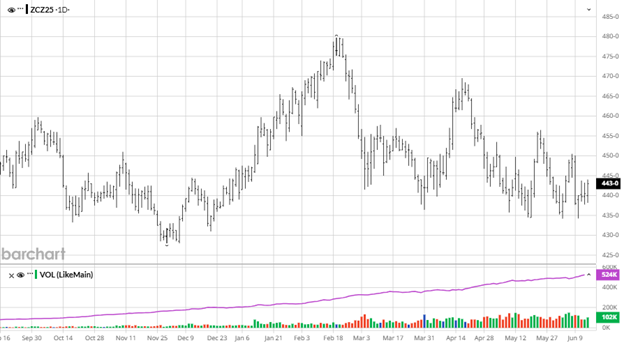
Corn continues to struggle with any rallies as you can see in the chart below every recent high is lower than the previous. The June 12th USDA report was lackluster with no real changes and not enough good news to give the bulls help. With the crop planted, 75% good/excellent, and non-threatening growing weather ahead, the bulls need a weather issue and/or positive trade news to change the direction of the market. The next major report is the June 30th Stocks and Acreage Report that tends to cause some volatility.

Via Barchart

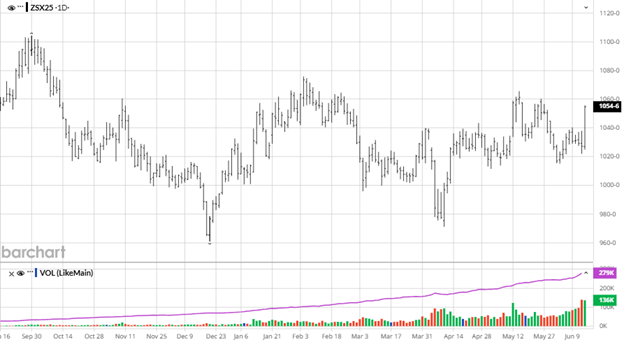
Soybeans received great news to end the week with better-than-expected biofuel mandates from the Trump administration. You can see how the news was received after a lackluster USDA report earlier in the week in the chart below. Beans will need to breakthrough recent highs or at least stay above the moving averages they broke through to keep some positive momentum as they are where they were back in February which is at least better than corn’s price movement. Planting should wrap up soon and good growing weather will move this crop along. Beans received one piece of good news in the biofuel mandates as they await news on any deal with China to help push higher.

Via Barchart

Equity Markets

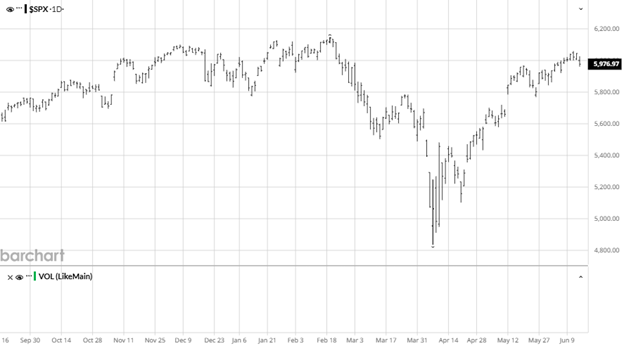
Markets have settled down after another V shape recovery following the tariff driven dip at the beginning of April. The leveling off slightly below all-time highs shows that the market is hesitant in what to expect moving forward but acknowledges that the initial reaction to tariffs with negotiations ongoing were an overreaction. While the market could fail here and move lower with negative trade news the biggest domino the market is watching is China while also keeping an eye on developments in the Middle East.

Via Barchart

Other News

  • Israel and Iran’s conflict appears to be getting worse with more attacks while the US tries to position itself to lower tensions. Crude Oil prices will watch the news as a global economic slowdown vs lower production due to war would face off.
  • Cotton has been quiet with a lack of foreign demand with global economic uncertainty.


Drought Monitor

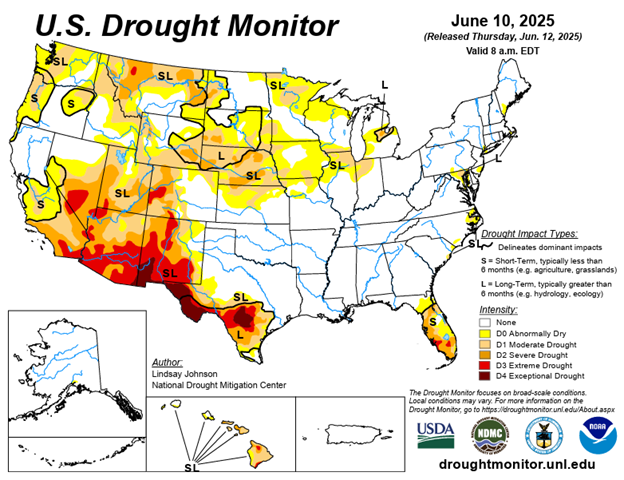
Here is the most recent drought monitor.

Contact an Ag Specialist Today

Whether you’re a producer, end-user, commercial operator, RCM AG Services helps protect revenues and control costs through its suite of hedging tools and network of buyers/sellers — Contact Ag Specialist Brady Lawrence today at 312-858-4049 or blawrence@rcmam.com.


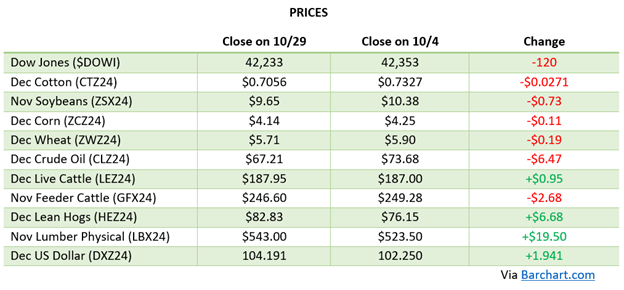
29 Oct 2024

AG MARKET UPDATE: OCTOBER 4 – 29

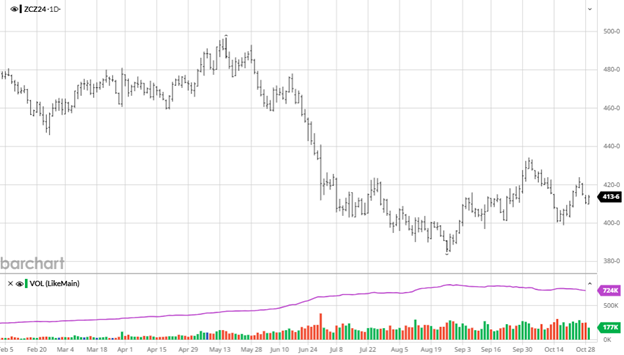
Corn has been range-bound the last 2 months between $4 and $4.40. With no weather issues during harvest following a very dry end of the growing season, the market did not get any unexpected help to push it higher. Mexico continues to buy US corn at a fast pace, appearing again in the export reports. With no major problems starting the year in South America and smooth sailing to the finish of US harvest there does not appear to be anything to give this market a boost. Expect technicals to play a major role in the direction of the trade for the near term as the fundamental trade will be reliant on harvest news.

Via Barchart

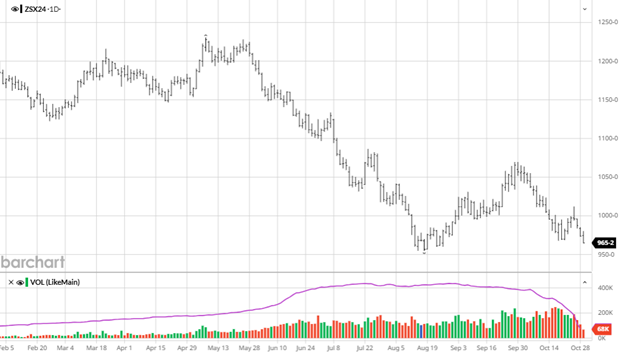
Soybeans weakness over the month has lowered it with corn. Beans do not have any bullish news on the horizon as they failed to rally through technical resistance. With the election next week, a tariff war with China would hurt beans in an already depressed market as we have seen in the past. Funds are very short and will need a catalyst to get them to change course, which currently is lacking. Bean harvest is 89% complete which means there won’t be much opportunity for unexpected bullish news moving forward.

Via Barchart

Equity Markets

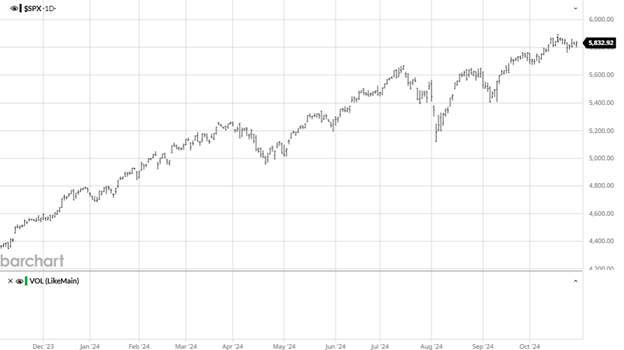
The equity markets continue higher as the biggest week of earnings kicks off. The Fed is expected to cut rates again by the end of the year, but inflation and jobs data are sending a mixed picture. The 10-year US treasuries have moved higher since the rate cut as the market is questioning whether or not the Fed will get it right.

Via Barchart

Other News

  • China announced that total grain production this year would be a record 700 million metric tons. As China continues to increase domestic production of edible commodities while continuing to invest in South America the US needs to find a new partner to replace their demand as they continue to try and be less reliant on American agriculture.
  • Crude Oil has been volatile but has moved lower this week as possible easing tensions in the Middle East as cease fire negotiations restart.
  • With the election results potentially being unknown for a few days following November 5 there could be some volatility in all markets.
  • The October insurance averages are $4.16 1/2 for corn and $10.06 for beans as of 10/29. The February insurance averages were $4.67 for corn and $11.60 for beans.

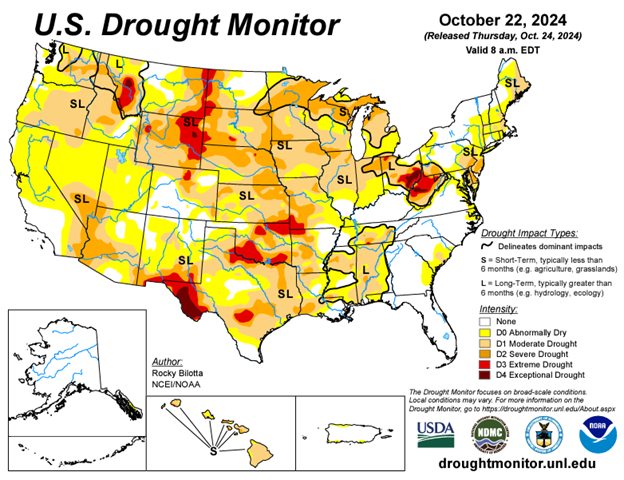
Drought Monitor

Contact an Ag Specialist Today

Whether you’re a producer, end-user, commercial operator, RCM AG Services helps protect revenues and control costs through its suite of hedging tools and network of buyers/sellers — Contact Ag Specialist Brady Lawrence today at 312-858-4049 or blawrence@rcmam.com.

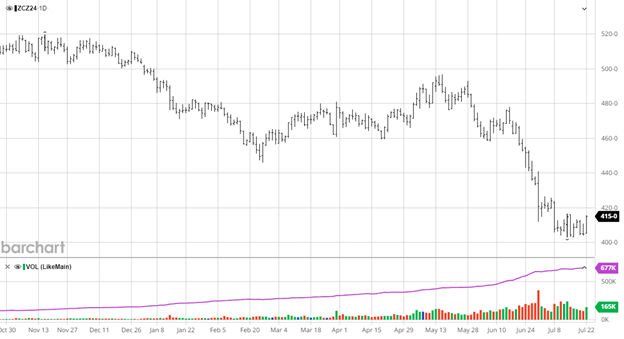
22 Jul 2024

AG MARKET UPDATE: JULY 8 – 22

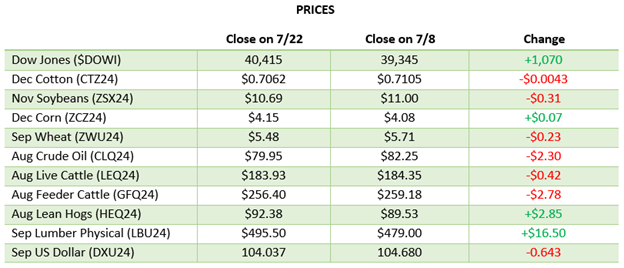
Corn has consolidated in the $4 to $4.20 range since July 8 even with the USDA report. The USDA did not release any major updates to production as they let expected US yield at 181 bu/ac but it did have lower ending stocks for the next 2 years with increased old crop exports and increased feed demand. This bullish news was not enough to put a fire behind corn as the US crop this year remains on record breaking pace with the great weather start to the year. The forecasts to start the week were adjusted for a warmer drier US starting this week than initially thought, lifting markets.

Via Barchart

Beans seemed to find a near term bottom last week trading into the low $10.30 range. The sharp rally to start the week was a welcome sign with the largest up day for the Nov contract in at least the last 6 months. The USDA made minimal changes to soybeans in their update while adding demand to offset potentially record yields in the US. As we head into the back half of summer the bean market will trade on export demand from China and US weather.

Via Barchart

Equity Markets

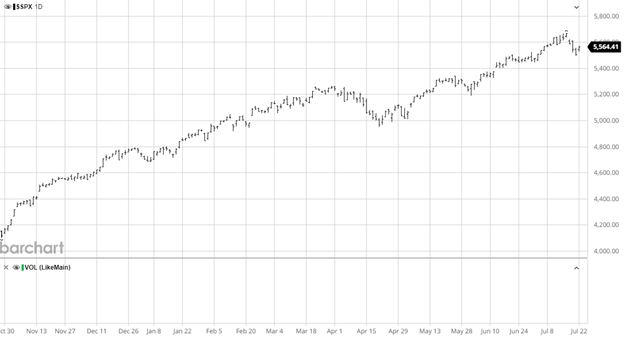
The equity markets have shown volatility in July as several mega cap stocks that had been driving the market fell last week while small cap stocks saw their best week in years. The market is expecting rate cuts in September and the moves of last week appear to be repositioning within the market as funds space out their funds more away from the biggest stocks.

Via Barchart

Other News

  • President Joe Biden announced he would not seek reelection in November and put his support behind Kamala Harris to be the Democrats nominee. The DNC is in Chicago next week where unless a challenger pops up, she will become the nominee.
  • An assassination attempt on former president and current GOP nominee Donald Trump occurred at a rally last week after a gunmen fired on him at the event hitting his ear and killing someone in attendance.
  • The Ag markets will pay attention to the election as tariffs and trade wars (potentially from both candidates) are on the table.
  • Cotton continues its weakness drifting lower as the US is trending towards a large crop at this point in the year with weak demand from the global market.

Drought Monitor


Via Barchart.com

Contact an Ag Specialist Today

Whether you’re a producer, end-user, commercial operator, RCM AG Services helps protect revenues and control costs through its suite of hedging tools and network of buyers/sellers — Contact Ag Specialist Brady Lawrence today at 312-858-4049 or blawrence@rcmam.com.


13 May 2024

AG MARKET UPDATE: APRIL 19 – MAY 10

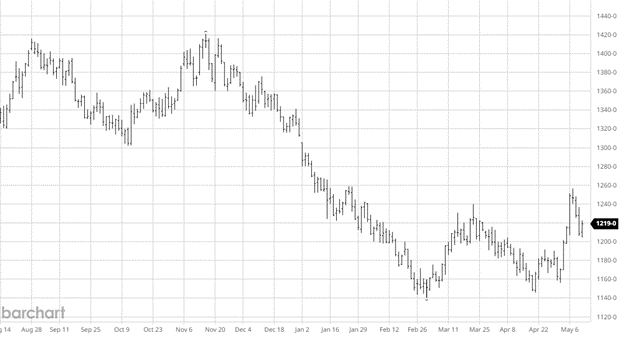
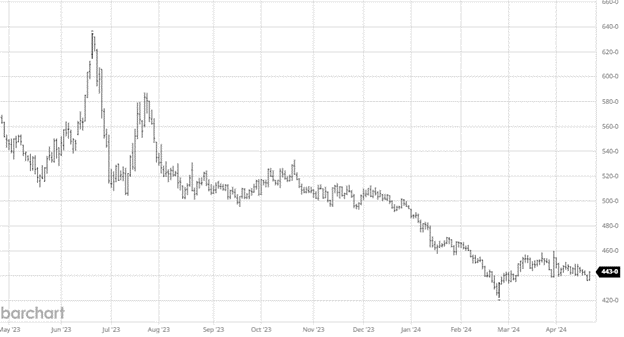
Corn has seen a strong rally over the last couple of weeks as planting is slightly delayed in parts of the US and funds seem to have changed their tone a bit. Last week’s USDA Report did not have any earth-shattering news but did provide some good news for the markets. US corn stocks were lower than estimates heading into the report along with world stocks for both 23/24 and 24/25. The production outlook for this year, 181 bu/ac, continues to show how the advances in agronomic practices and seed genetics continue to grow. All of these carryout and stocks numbers are based on those production estimates so if we begin to see weather issues or problems at the end of planting, we could continue to see revisions to the downside, and vice versa with great weather and conditions.

Via Barchart

Beans had a rough week after a strong start to May. The USDA Report leaned bearish as the South American production continues to expand for the upcoming year. The USDA is slowly trimming Brazil’s bean crop but is still above CONAB’s estimates by a bout 300 million bushels. The recent flooding in southern Brazil will force their hand to lower their expectations but the CONAB estimates on losses will be closely watched. Another promising development in the report was the expectation of record imports and usage in China. While much of this is expected to be met by Brazil and issues with their production will still need to be met.

Via Barchart

Equity Markets

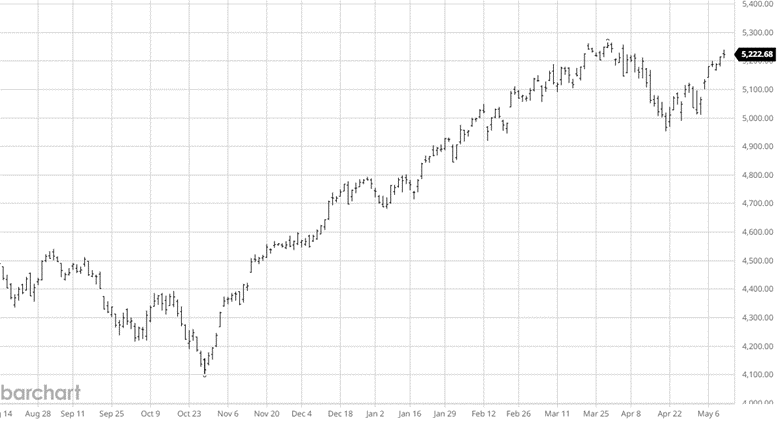
The equity markets have rebounded over the last couple weeks with earnings season going on. The feeling on Fed rate cuts keeps pushing them back with one not expected until the fall and at least one fed chair thinking we may not get one this year as inflation remains sticky. Rates will remain data dependent but the feeling of higher for longer continues to seem more likely.

Via Barchart

Cotton

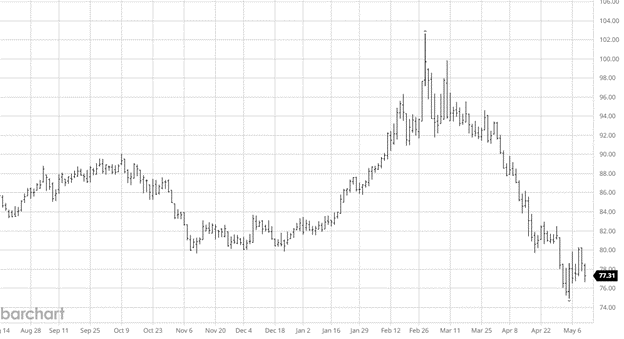
  • Cotton has fallen well off the February and March highs as the lack of demand in the global market mixed with funds exiting their long positions has beaten down the market.

Via Barchart

Wheat

  • Wheat’s recent rallies are welcome after struggling to find much positive movement in the market to start the year. Frost damage to Russia’s wheat crop and a dry pattern in the Black Sea has been the recent mover as the USDA Report had some mixed numbers. Smaller than expected US stocks, 24/25 world stocks and total production with higher than expected world wheat stocks for 23/24.

Other News

  • Conflict continues between Israel and Palestine as a ceasefire has been negotiated on many sides, but nothing has been agreed to yet.
  • Major flooding across southern Brazil has killed thousands of livestock and will have an impact on their crop but the extent of which is not known yet

Drought Monitor

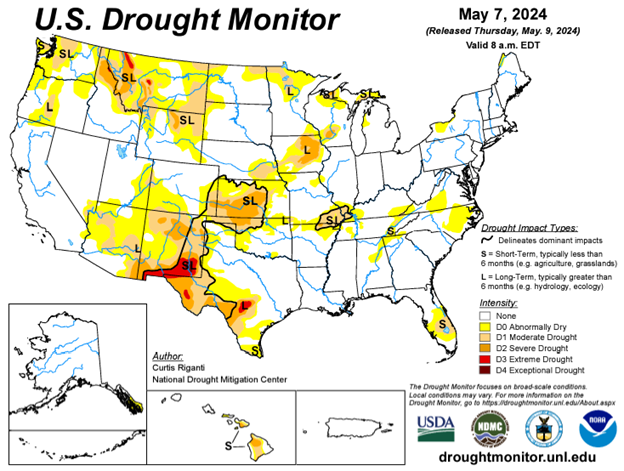
Here is the current drought monitor as we head toward planting with subsoil moisture a focus.

Via Barchart.com

Contact an Ag Specialist Today

Whether you’re a producer, end-user, commercial operator, RCM AG Services helps protect revenues and control costs through its suite of hedging tools and network of buyers/sellers — Contact Ag Specialist Brady Lawrence today at 312-858-4049 or blawrence@rcmam.com.


22 Apr 2024

AG MARKET UPDATE: APRIL 8 – 19

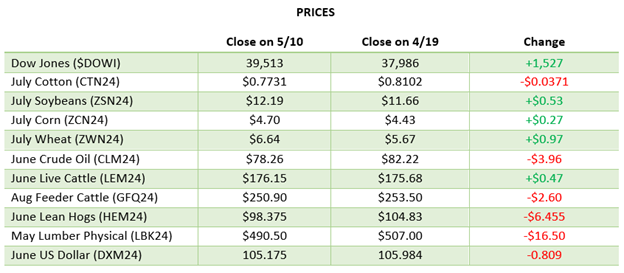
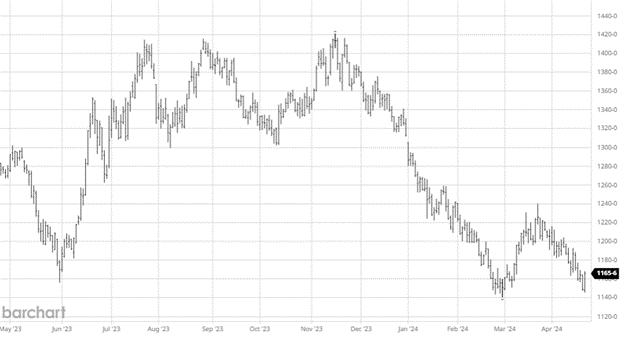
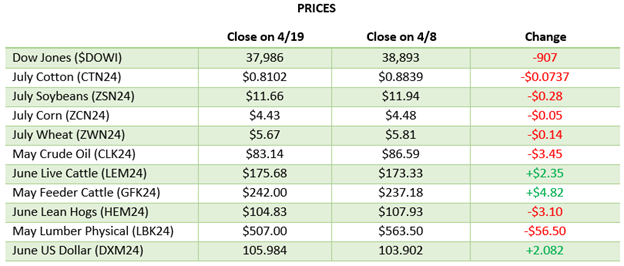
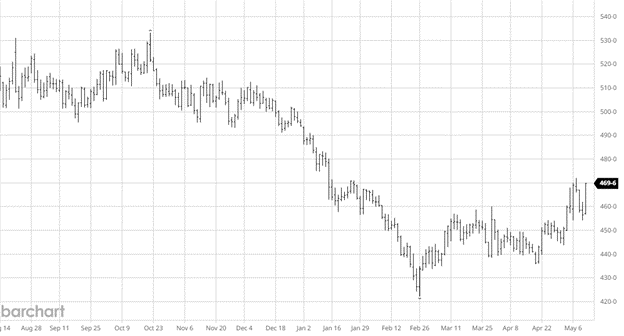
Corn continued its slow bleed lower over the last couple weeks with no major bullish news to turn this market around. US weather may slow planting down to end April a bit but not enough for markets to begin to worry anytime soon. Argentina’s rain will continue to slow harvest as the discrepancy between the USDA and South American reporting services remains a mystery. The bounce to end the week was due to escalation of the Israel and Hamas/Iran fighting in the middle east.  According to Reuters the US EPA is expected to announce plans to temporarily waive restrictions on higher-ethanol gasoline blends this summer. This market is at the mercy of funds and weather which currently aren’t helping prices higher.
Via Barchart

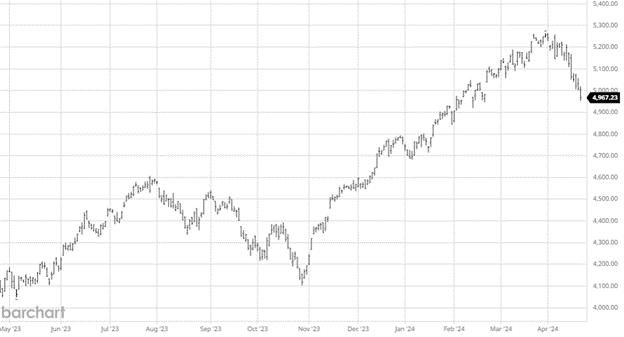
Beans continued lower as they lost another 20+ cents this week even with the big up day on Friday. Beans need any good news they can get as you can see from the chart below it has been a rough few months. Soybean oil has also had a rough go lately as bullish news is lacking in the soybean complex. The size of the bean harvest with the USDA and CONAB numbers still far apart will be the biggest factor moving forward as we need all the information we can get. We did get close to the technical support which is good to see a bounce there.

Via Barchart

Equity Markets

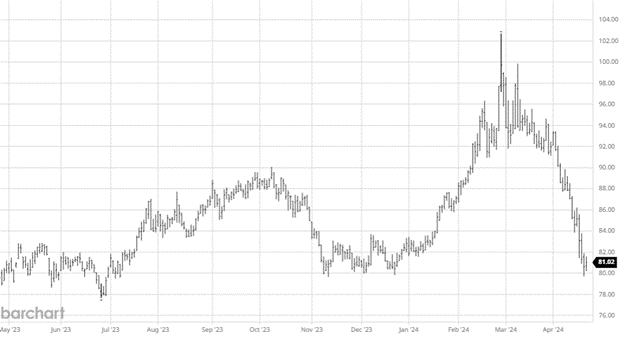
The equity markets continued their recent struggles as tech and AI stocks have given back some recent gains. Pullbacks are healthy for markets, especially after the run we have had to start the last few months being so concentrated, but sticky inflation and war escalation provides some problems to monitor as earnings are set to ramp up next week.

Via Barchart

Other News

  • Israel retaliated against Iran overnight continuing the escalation of tensions and war in the middle east.
  • The USD keeps moving higher as the June USD Index went over 106 earlier this week.
  • Cotton has struggled of late as a lack of demand on the global scale and no weather issues yet in the US pulled it back from recent highs.

Via Barchart

Drought Monitor

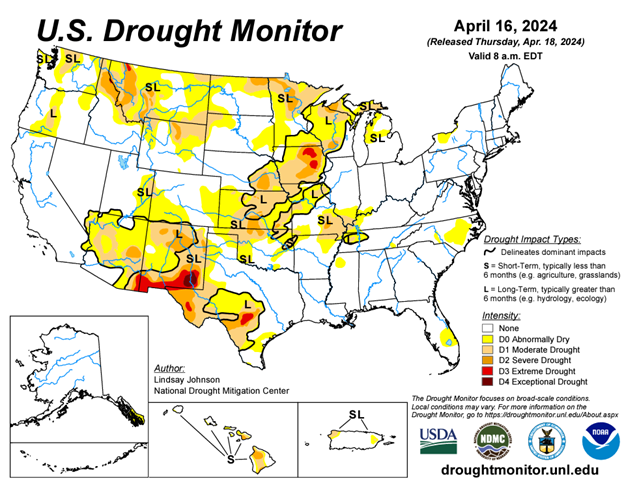
Here is the current drought monitor as we head toward planting with subsoil moisture a focus.

Via Barchart.com

Contact an Ag Specialist Today

Whether you’re a producer, end-user, commercial operator, RCM AG Services helps protect revenues and control costs through its suite of hedging tools and network of buyers/sellers — Contact Ag Specialist Brady Lawrence today at 312-858-4049 or blawrence@rcmam.com.