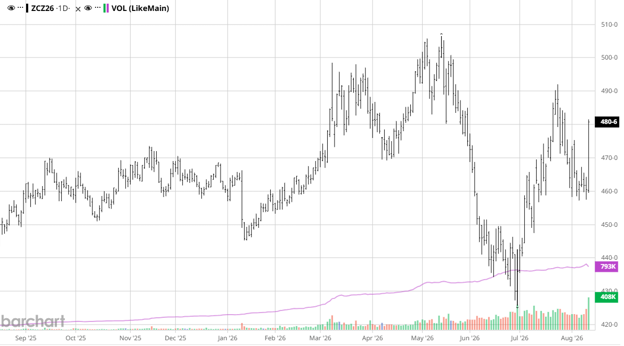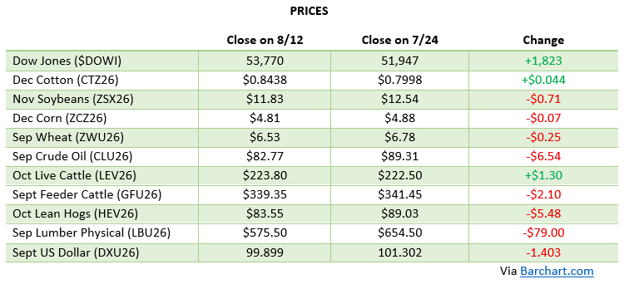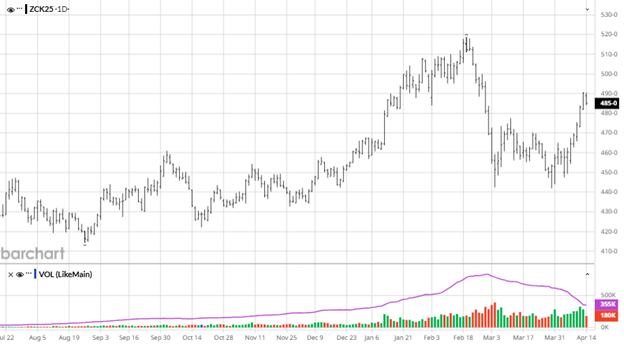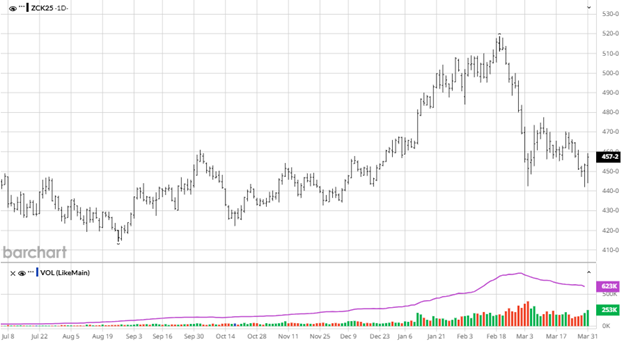

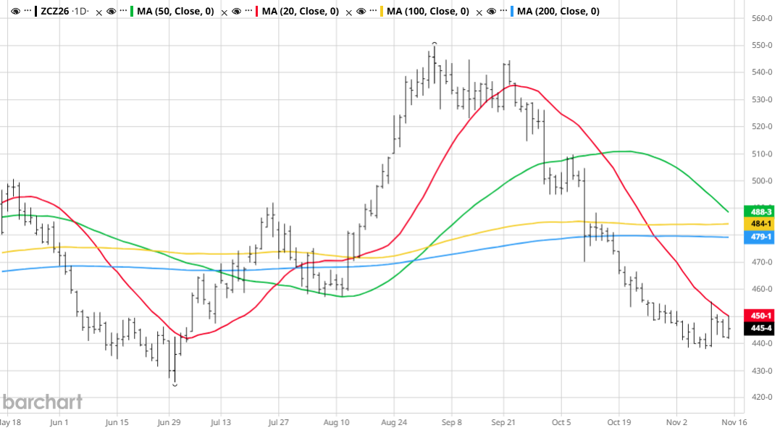
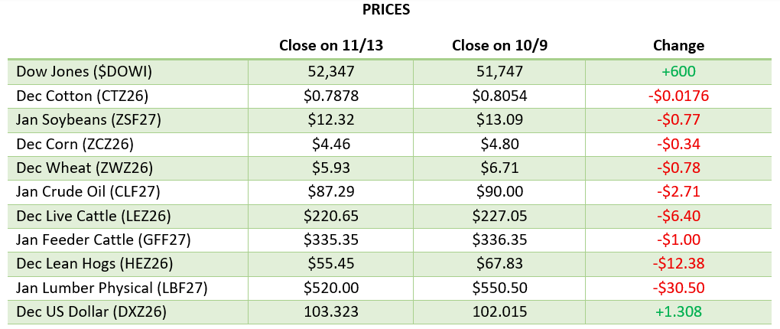
Corn opened this period with one of the most bearish USDA surprises in years. The October 9th WASDE raised the national yield 2.7 bushels per acre to 181.2 bpa, the largest September-to-October jump since 2005, when the trade was looking for a cut to roughly 177.7. That pushed production above 16 billion bushels, lifted 2026/27 ending stocks 282 million bushels to 1.849 billion, and sent stocks-to-use back above 10%. December futures briefly traded limit down, and the funds that had built a record net long in early September headed for the exits, slashing their net long from roughly 231,000 contracts in mid-October to about 56,000 by October 27th. Add in harvest pressure and export inspections running about half of last year’s pace, and December corn slid to $4.39 by November 9th, its lowest since mid-August and more than $1.10, or 20%, off the $5.50 high posted September 2nd.
The November 10th WASDE flipped the script. USDA cut yield 1.6 bpa to 179.6, below the 180.3 trade average, with Illinois down 8 bushels to 200 and Indiana down 5 to 195. Production fell 141 million bushels to 15.893 billion and, even after trimming exports to 3.275 billion, ending stocks dropped to 1.758 billion (10.8% stocks-to-use). December corn jumped nearly 10 cents to $4.49 on report day, but the rally lacked follow-through and settled at $4.42½ on Thursday as a stronger dollar, weak wheat, and favorable Brazilian weather weighed. With harvest only 81% complete as of November 8th, five points behind average and slowed by wet conditions in Iowa, some analysts think USDA may trim yield further before the final number in January. Between now and the next update, watch the 20-day moving average near $4.50 in Dec as overhead resistance, the weekly export pace, and early-season weather for Brazil’s crop.

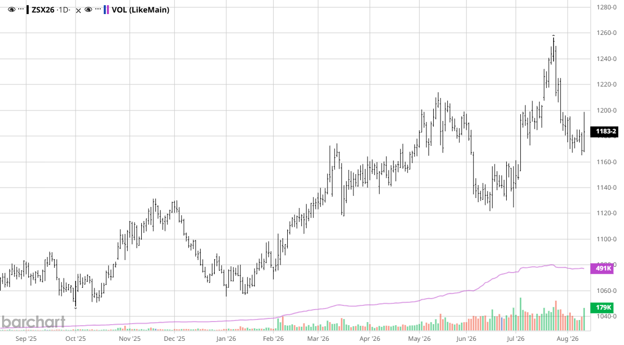
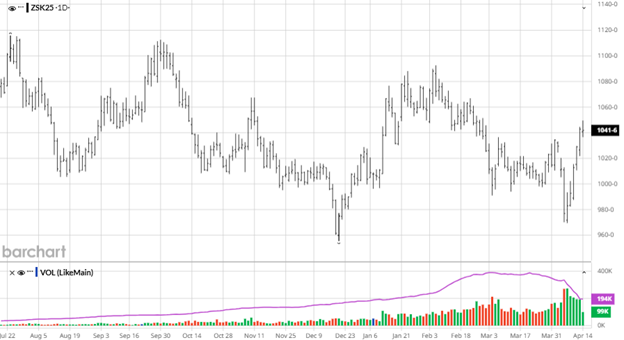
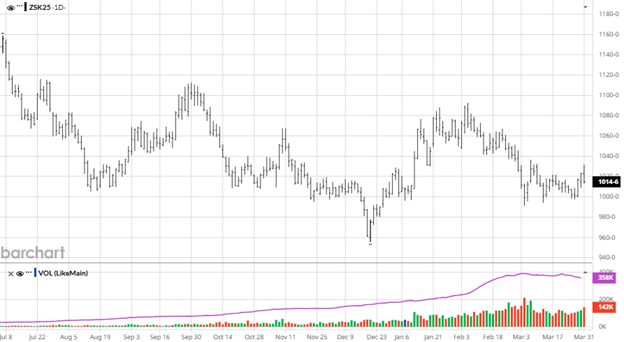
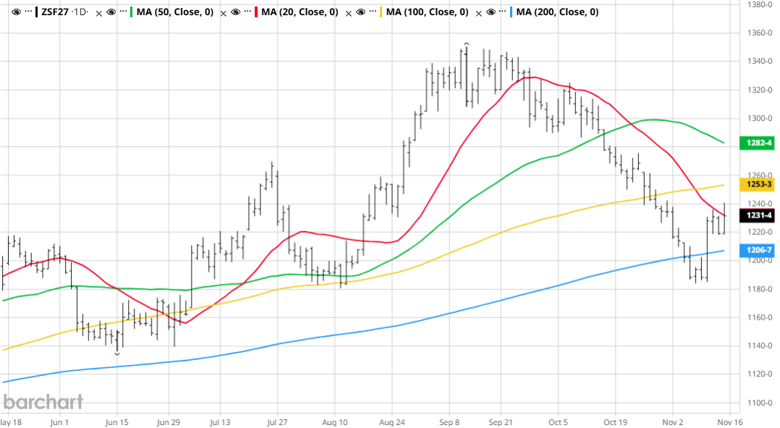
Soybeans followed a similar round trip. The October report was neutral to slightly bearish, with yield raised to a record 53.1 bpa and ending stocks at 315 million bushels, and beans bled lower through October as harvest raced ahead. The bigger blow came from Brazil, where Lula’s surprise October 25th runoff victory sent the real roughly 11% lower, making Brazilian beans cheaper on the world market and knocking November soybeans down 34¼ cents that week. January futures bottomed at $11.84 last week, about 12% below the September 11th high near $13.50, before China stepped back in with announced purchases on five of six business days into November 6th. The November WASDE then delivered a friendly surprise: yield rose only to 53.3 bpa against a 53.6 trade guess (and whispers near 55), exports were raised, and ending stocks fell 15 million bushels to a tight 300 million, a 6.5% stocks-to-use, while the season-average price was raised 10 cents to $12.10. January beans rallied nearly 40 cents to $12.28 on report day before profit-taking pulled them back to $12.19 Thursday. The next major catalyst is the Trump-Xi meeting at the APEC summit in Shenzhen on November 18th-19th, though observers expect major deliverables may wait for the G20 in Miami in mid-December. Brazilian planting weather and the pace of Chinese sales remain the other key watch items.
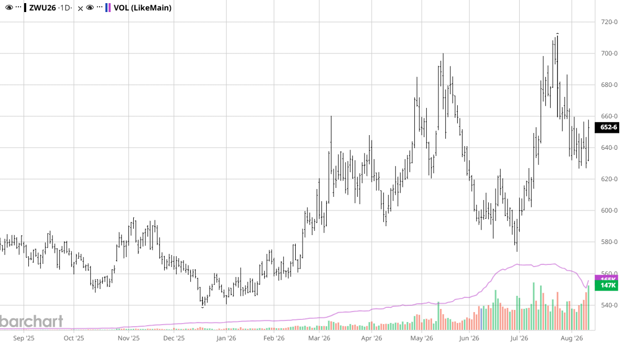
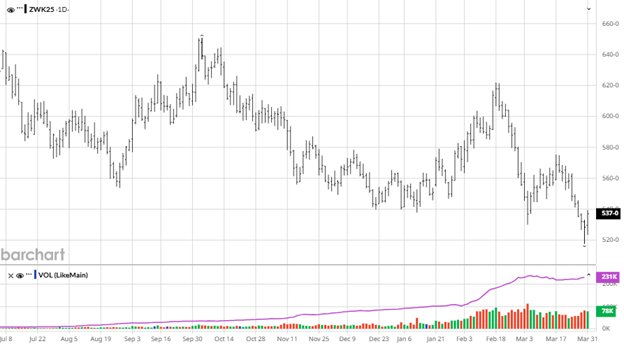
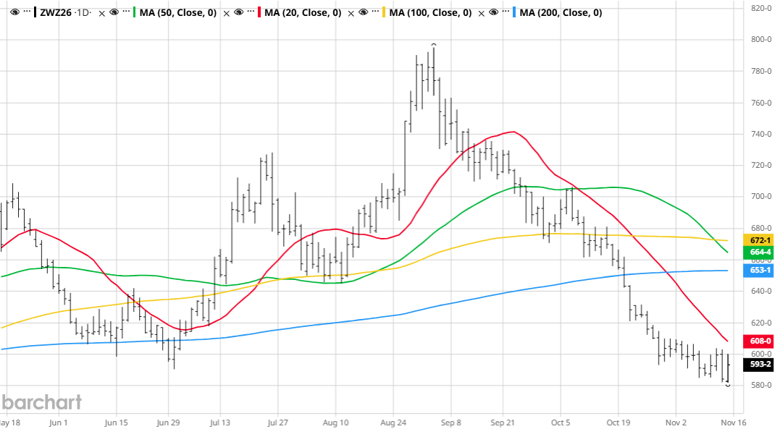
 Wheat has been the weakest link in the complex, extending its losing streak to nine straight weeks into early November. Managed money flipped from long to short in Chicago and has kept pressing, with the net short reaching roughly 88,700 contracts as of the most recent report. The main driver has been diplomacy: U.S.-brokered Russia-Ukraine talks in Abu Dhabi on November 10th-11th, the first such discussions since February, have raised hopes that Black Sea grain flows could eventually be restored, and Russia temporarily resumed some Sea of Azov shipments under Kerch Strait permits valid through November 15th. The November WASDE added to the pressure, leaving U.S. production unchanged at 1.534 billion bushels, nudging ending stocks up to 743 million, and raising world ending stocks 4.8 million metric tons to 280.8 million, well above trade expectations. December Chicago SRW settled at $5.84¼ on Thursday, down from above $7.30 in early September. Going forward, the outcome of the Russia-Ukraine talks is the swing factor, and with funds carrying a large short, any breakdown in negotiations or renewed Black Sea disruption could trigger sharp short-covering.

Equity Markets
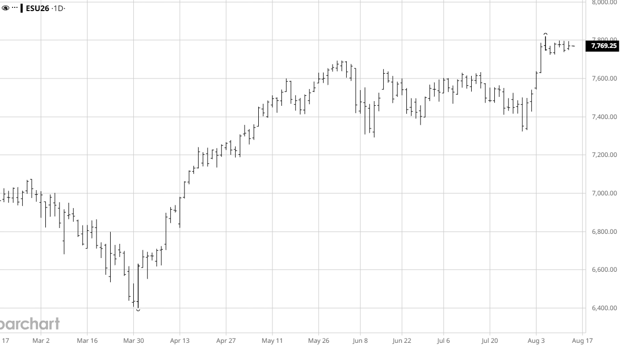
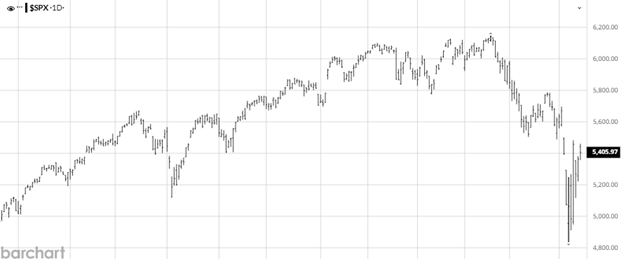
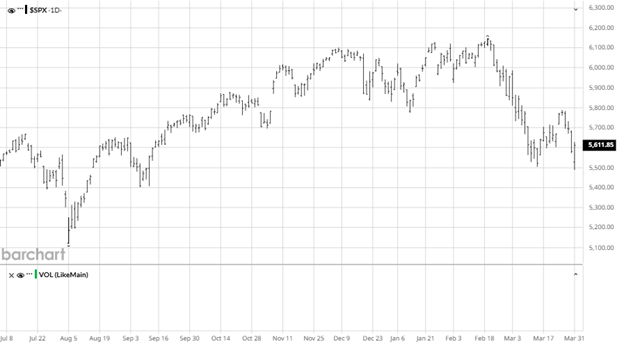
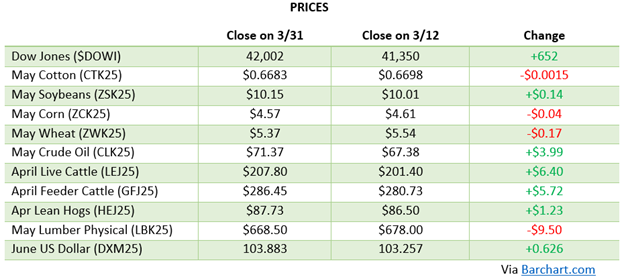
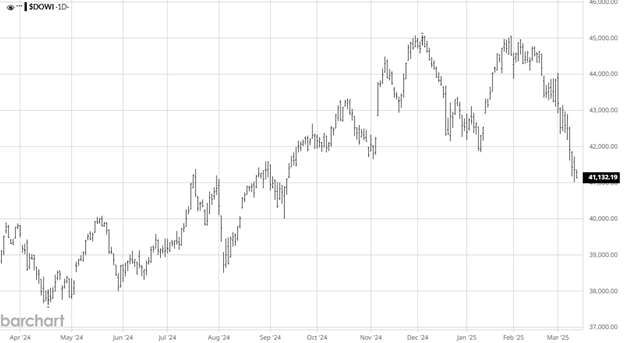
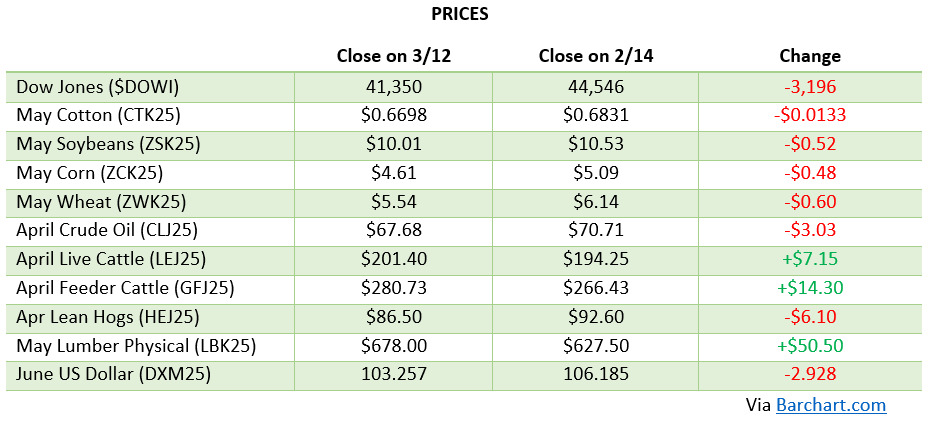
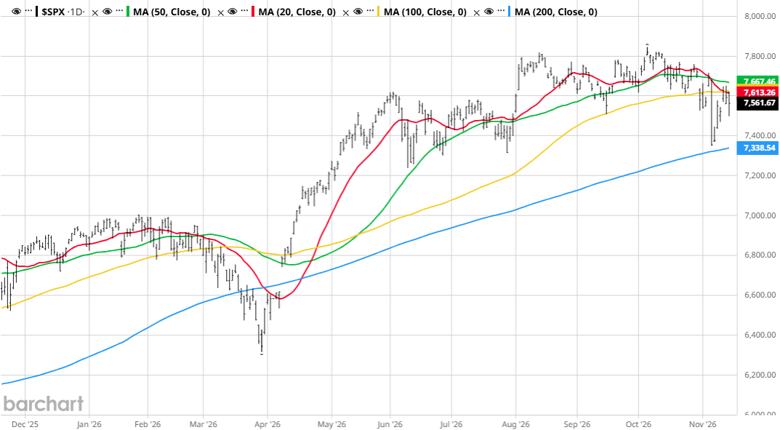
Equity markets have been on a roller coaster. Stocks slid for four straight weeks into early November as concerns over AI financing and data center spending collided with the midterm elections, and the S&P 500 fell 2.7% in the first week of November alone. Wall Street then recovered most of those losses on November 9th, with the Dow jumping more than 1,100 points to 52,389 as oil prices fell, before a hotter-than-expected inflation report on November 10th revived rate-hike fears. That is the backdrop to watch: after hiking in September and holding with two hawkish dissents on October 28th, the Fed is widely expected to raise rates again at its December 8th-9th meeting, with the 10-year Treasury yield already north of 5%. It also doesn’t help when the CEO of the largest company in the world is forced to resign amongst scandal.
Energy Markets
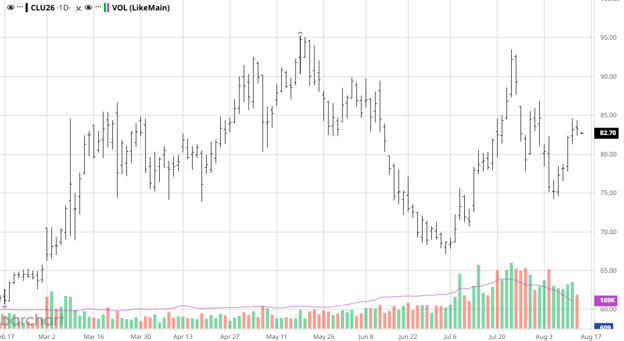
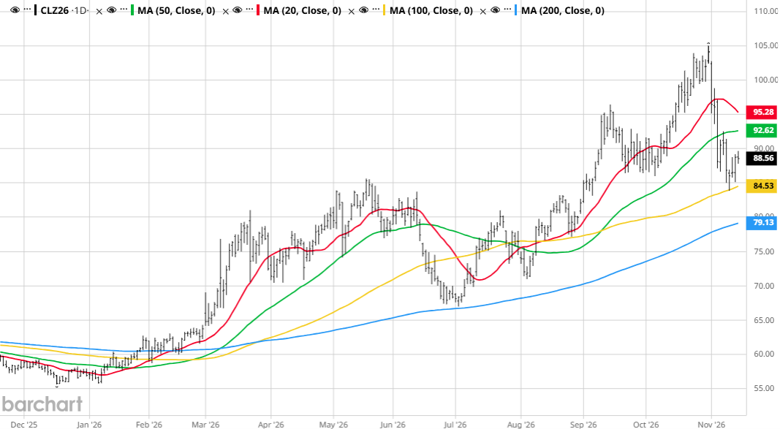
Crude oil continues to take its cues from the war with Iran, now in its ninth month. Prices rallied through October, with Brent hitting a six-month high and November WTI trading above $100 per barrel, before diplomacy took over after the midterms. President Trump said further strikes are highly unlikely as long as talks progress, and Brent fell to its lowest level since late August with crude posting its steepest weekly decline since 2020. December WTI bounced $2.33 to $88.94 on Thursday, a reminder that physical barrels remain tight and Strategic Petroleum Reserve holdings are at their lowest since 1982. For producers, any lasting peace deal would bring welcome relief on diesel and fertilizer costs, but analysts caution that normal Hormuz flows could take months to return even with an agreement.
Other News
– The Trump-Xi meeting at APEC in Shenzhen (November 18th-19th) is the most important near-term demand event for soybeans. The U.S.-China trade truce has been extended to January 10th, and the leaders are expected to meet again at the G20 in Miami on December 14th-15th.
– Cattle futures sold off sharply as USDA continued its phased reopening of the Mexican border to feeder cattle, with Columbus, New Mexico becoming the third crossing to reopen on October 26th and Nogales scheduled next. December live cattle fell more than $10 in one week in late October, and November feeders dropped another $15.45 the following week.
– Hogs were the weakest livestock market, with December lean hogs down 9% in the week ending November 6th and speculators holding a record net short of more than 50,000 contracts.
– USDA cut U.S. cotton production 267,000 bales to 13.18 million bales in the November WASDE, while harvest is running well ahead of normal.
– Brazil’s post-election weaker real is a lingering headwind for U.S. export competitiveness across soybeans, corn, and cotton heading into the South American growing season.
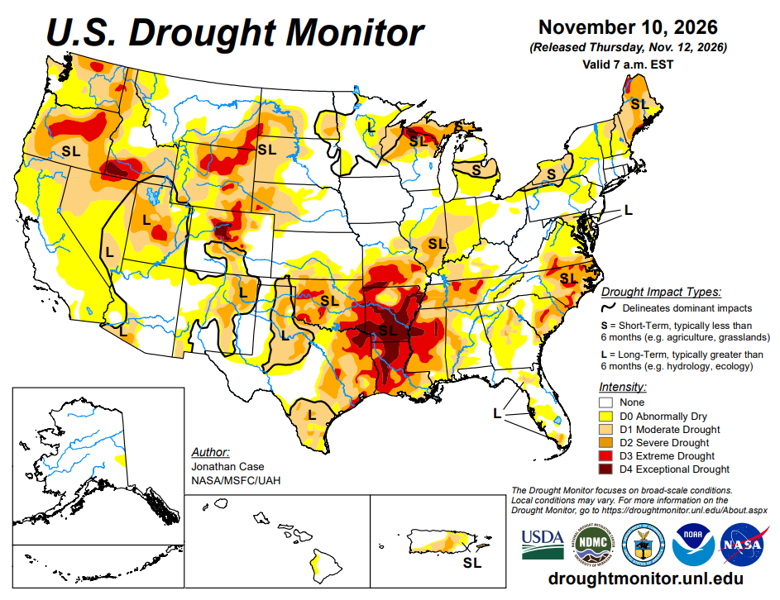
Drought Monitor
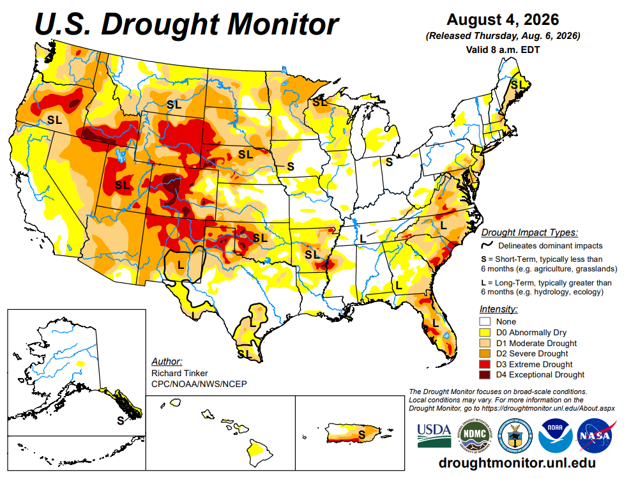
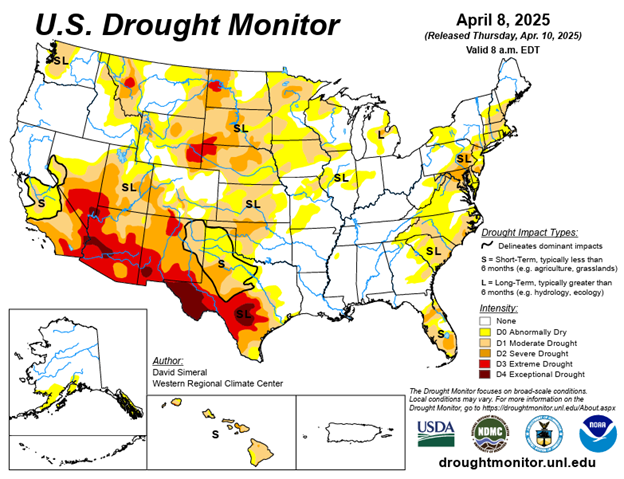
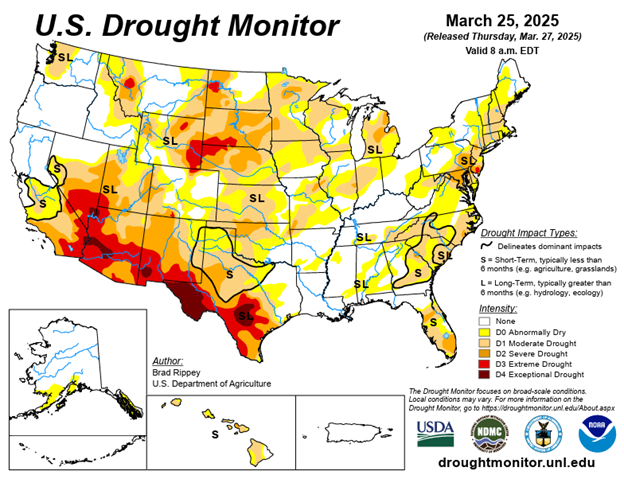
Here is the most recent drought monitor with harvest nearing its end.
Contact an Ag Specialist Today
Whether you’re a producer, end-user, commercial operator, RCM AG Services helps protect revenues and control costs through its suite of hedging tools and network of buyers/sellers — Contact Ag Specialist Brady Lawrence today at 312-858-4049 or blawrence@rcmam.com.